
What should I know about filing a roof damage insurance claim after a storm?
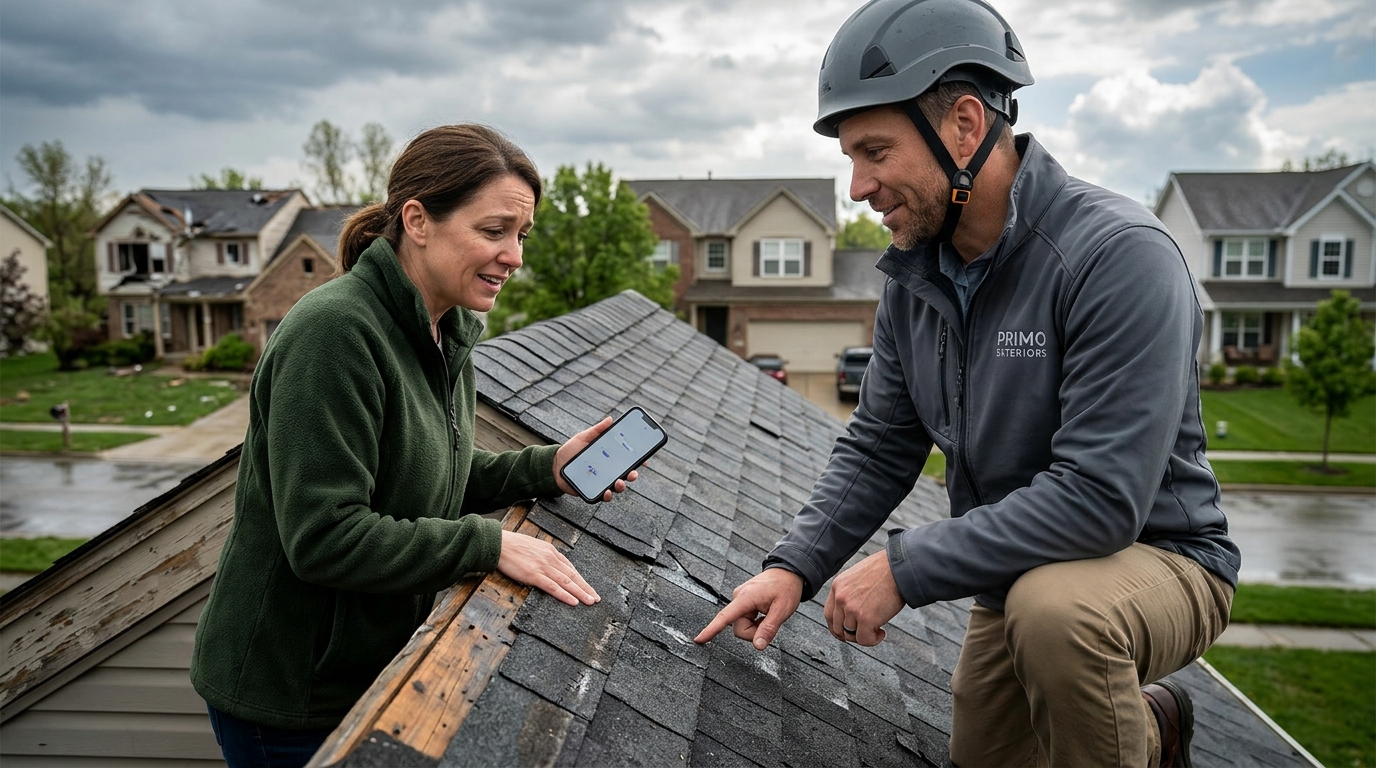
Filing a roof damage insurance claim after a storm requires immediate documentation, a professional inspection, and careful coordination with your insurance adjuster. Homeowners in Ohio often face complex weather events that cause hidden structural issues. Primo Exteriors provides specialized storm damage remediation and insurance claim assistance to ensure your property meets all code requirements during restoration. Understanding the process helps you secure the compensation you are entitled to under your policy.
Documenting Damage Before the Adjuster Arrives
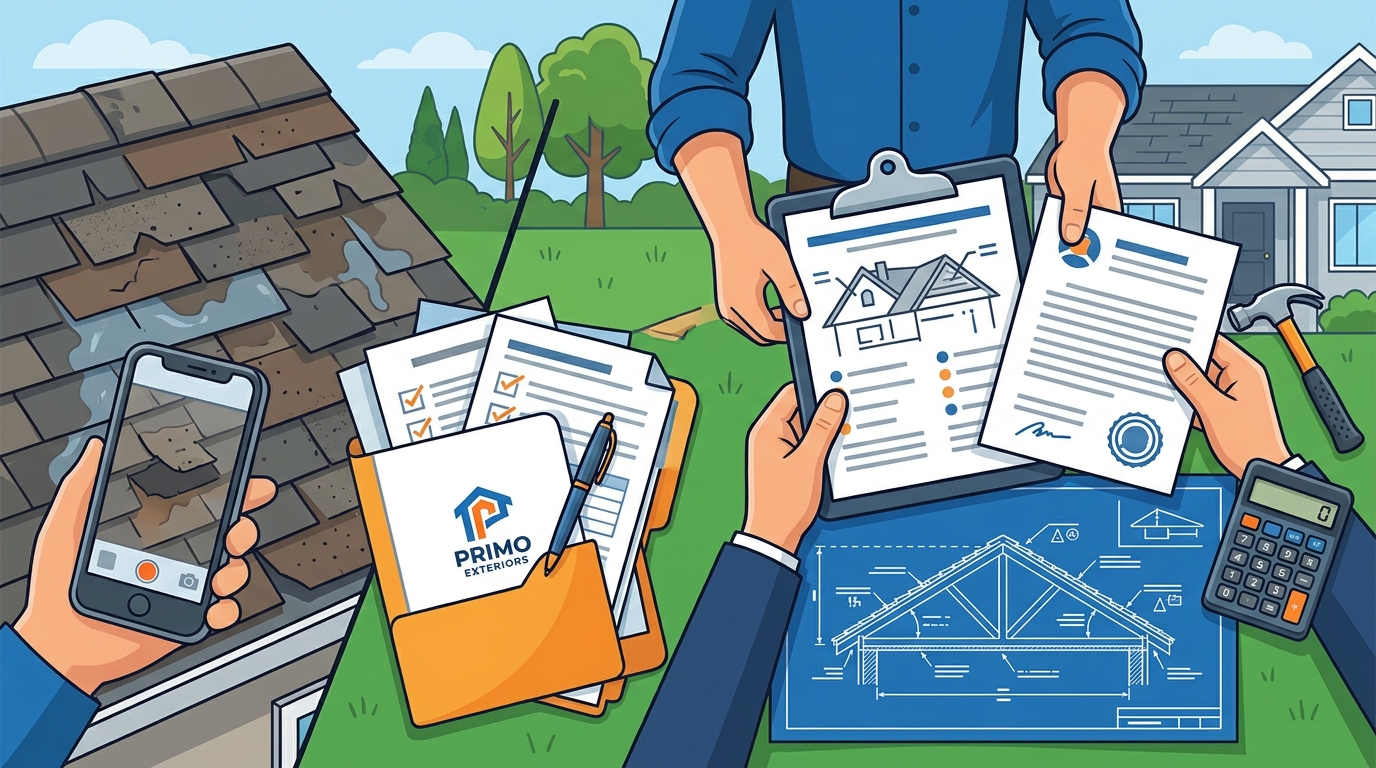
The first step in any successful claim is thorough documentation. You must capture the extent of the damage before any repairs begin. Take high-resolution photographs and videos of every affected area, including the roof, siding, gutters, and landscaping. Texas Department of Insurance advises homeowners to be present when the adjuster visits and to point out all damage. This proactive approach ensures that no minor issues are overlooked during the initial assessment.
Creating a Damage Inventory
Create a detailed list of all damaged items and structural components. Note the date of the storm and any prior maintenance records. This inventory serves as a baseline for your claim. It also helps you track the progress of repairs and verify that the final payout covers all necessary work.
The Role of Professional Roof Inspections
Insurance companies rely on professional inspections to determine the scope of repairs. A licensed contractor can identify hidden damage that is not visible from the ground. Primo Exteriors offers free roof inspections and consultations to diagnose problematic areas. Their team creates a detailed report that you can share with your insurance provider. This report acts as a bridge between your observations and the adjuster's evaluation.
Why Independent Estimates Matter
Getting multiple bids from contractors is a critical part of the process. Compare these bids with the adjuster's report before settling the claim. An independent estimate ensures that the insurance company's valuation aligns with actual market rates for materials and labor. This step protects you from underestimating the true cost of restoration.
Understanding Your Policy Coverage
Knowing the specifics of your insurance policy is essential for managing expectations. Replacement cost coverage is a common feature in many homeowners policies. Texas Department of Insurance explains that if you have replacement cost coverage, the company will pay with two checks. The first check is a partial payment, and the second is issued after the work is completed. Understanding this structure helps you plan your cash flow during the repair process.
Deductibles and Out-of-Pocket Costs
Coordinating with the Insurance Adjuster
Negotiating the Settlement
Avoiding Predatory Contractor Practices
After a major storm, homeowners are vulnerable to predatory practices by unscrupulous contractors. These "storm chasers" often prioritize profit over quality, leading to inflated prices and subpar work. Primo Exteriors warns that these practices harm homeowners who need quick and dependable repairs. It is essential to research reputable companies and check references before hiring anyone. A trusted local contractor will prioritize your best interests and ensure that your home is restored to code. according to How to File
Verifying Contractor Credentials
Always verify that a contractor is fully licensed and insured. This protects you from liability in case of accidents on your property. It also ensures that the work meets local building codes. Ask for proof of insurance and licensing before signing any contract. This due diligence is a simple step that can save you from significant financial and legal headaches.
Key Takeaways
- Document all damage with photos and videos before the adjuster arrives.
- Obtain a professional inspection to identify hidden structural issues.
- Understand your policy's coverage type, including replacement cost and deductibles.
- Be present during the adjuster's visit to point out all damage.
- Get multiple bids from contractors to compare with the adjuster's report.
- Verify that your contractor is licensed, insured, and reputable.
- Save proof of deductible payments and keep all claim documentation organized.
Frequently Asked Questions
How long does it take to process a roof damage insurance claim?
The timeline varies depending on the complexity of the damage and the insurance company's workload. Simple claims may be resolved in a few weeks, while complex cases can take several months. Working with a professional contractor can help expedite the process by providing clear documentation.
Can I choose my own contractor for insurance repairs?
Yes, you generally have the right to choose your own contractor. However, the insurance company may have preferred vendor lists. You are not required to use them, but using a preferred vendor might simplify the approval process. Always ensure your chosen contractor is licensed and insured.
What if the insurance company denies my claim?
If your claim is denied, you have the right to appeal the decision. Review the denial letter carefully and gather additional evidence to support your case. A professional contractor can help you prepare a rebuttal with detailed documentation and expert opinions.
Do I need to pay the deductible before repairs start?
Yes, you are responsible for paying the deductible. The insurance company will deduct this amount from the total payout. Save your receipt or proof of payment, as the insurance company may request it before issuing the final check.
How can I protect my home from future storm damage?
Regular maintenance is key to preventing storm damage. Schedule annual inspections for your roof, siding, and gutters. Address minor issues promptly to prevent them from becoming major problems. Primo Exteriors offers gutter cleaning and maintenance services to keep your home protected year-round. according to How to Write
Next Steps for Homeowners
Navigating a roof damage insurance claim can be stressful, but with the right preparation and professional support, you can secure the compensation you need. Primo Exteriors is committed to helping homeowners in Cincinnati and Dayton through every step of the process. From initial inspection to final restoration, their team ensures that your home is safe, secure, and compliant with all building codes. To start your claim or schedule an inspection, request a free quote today.